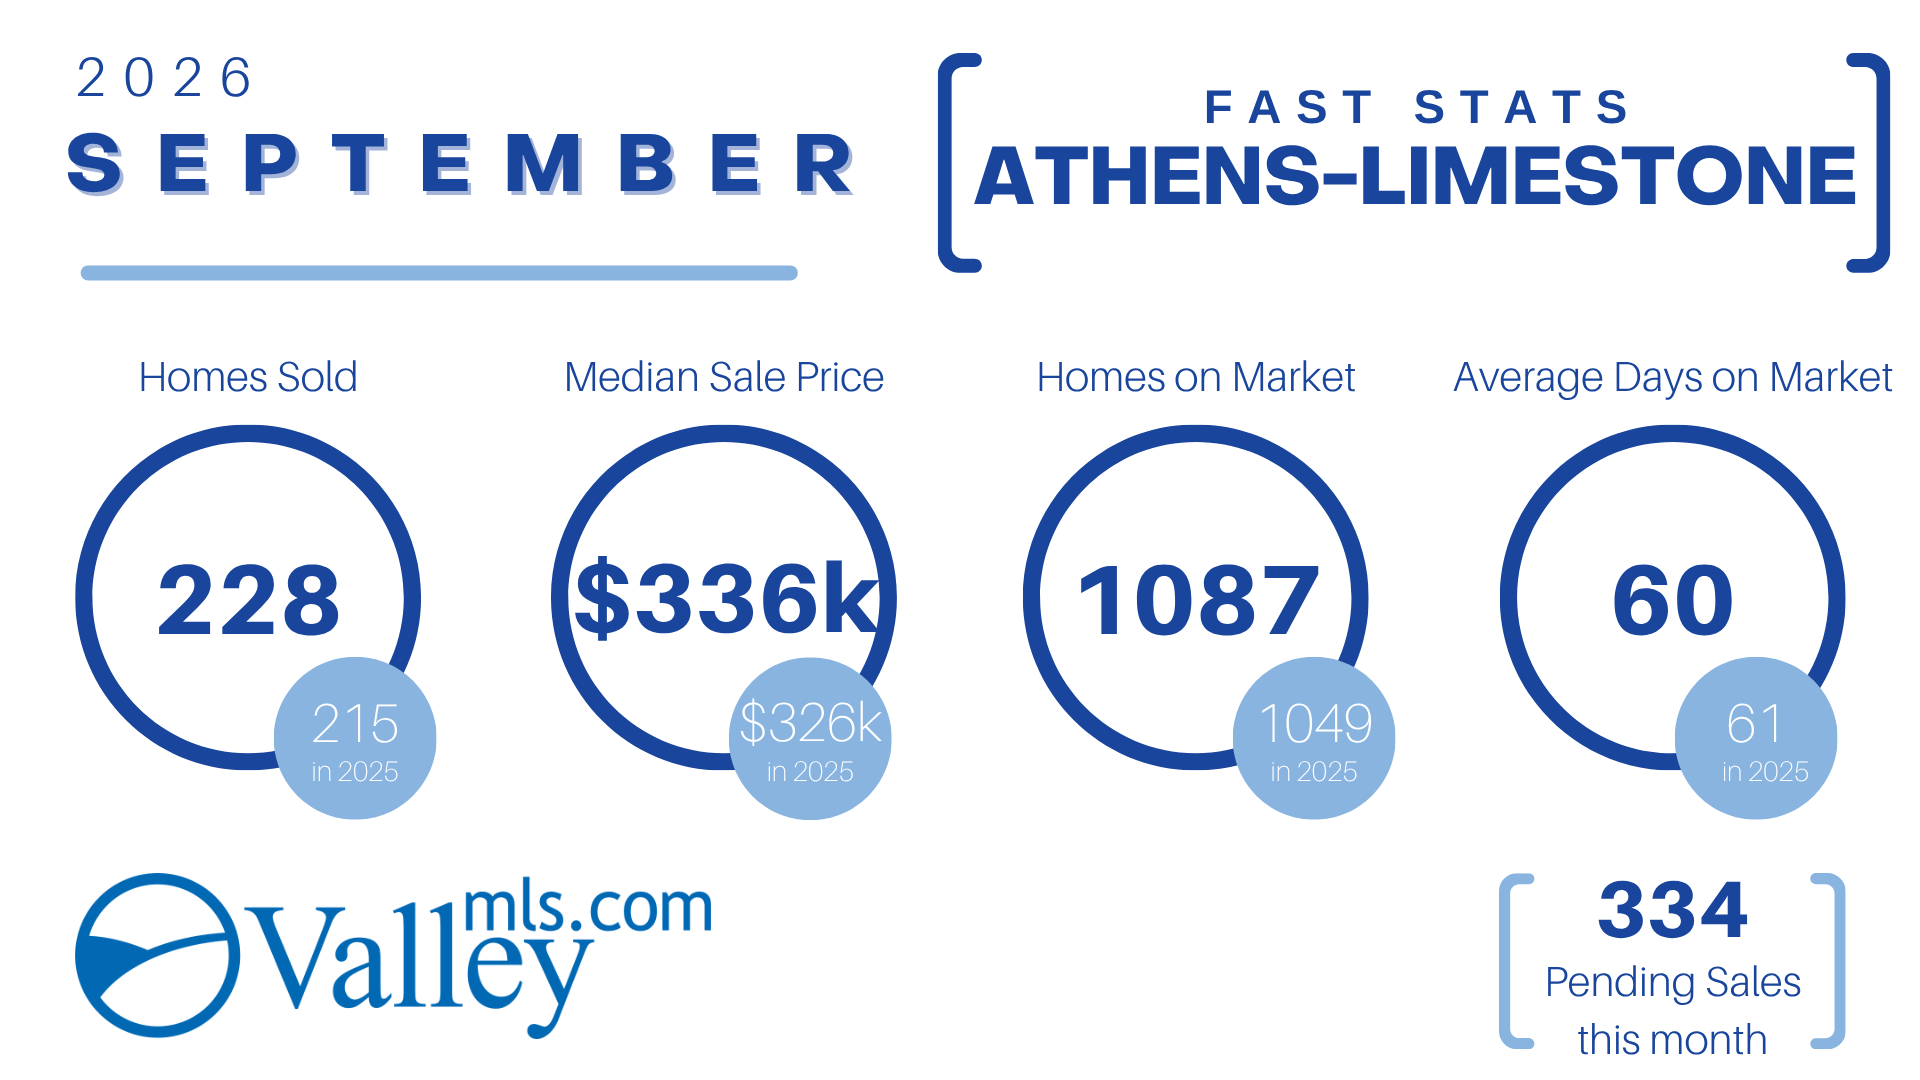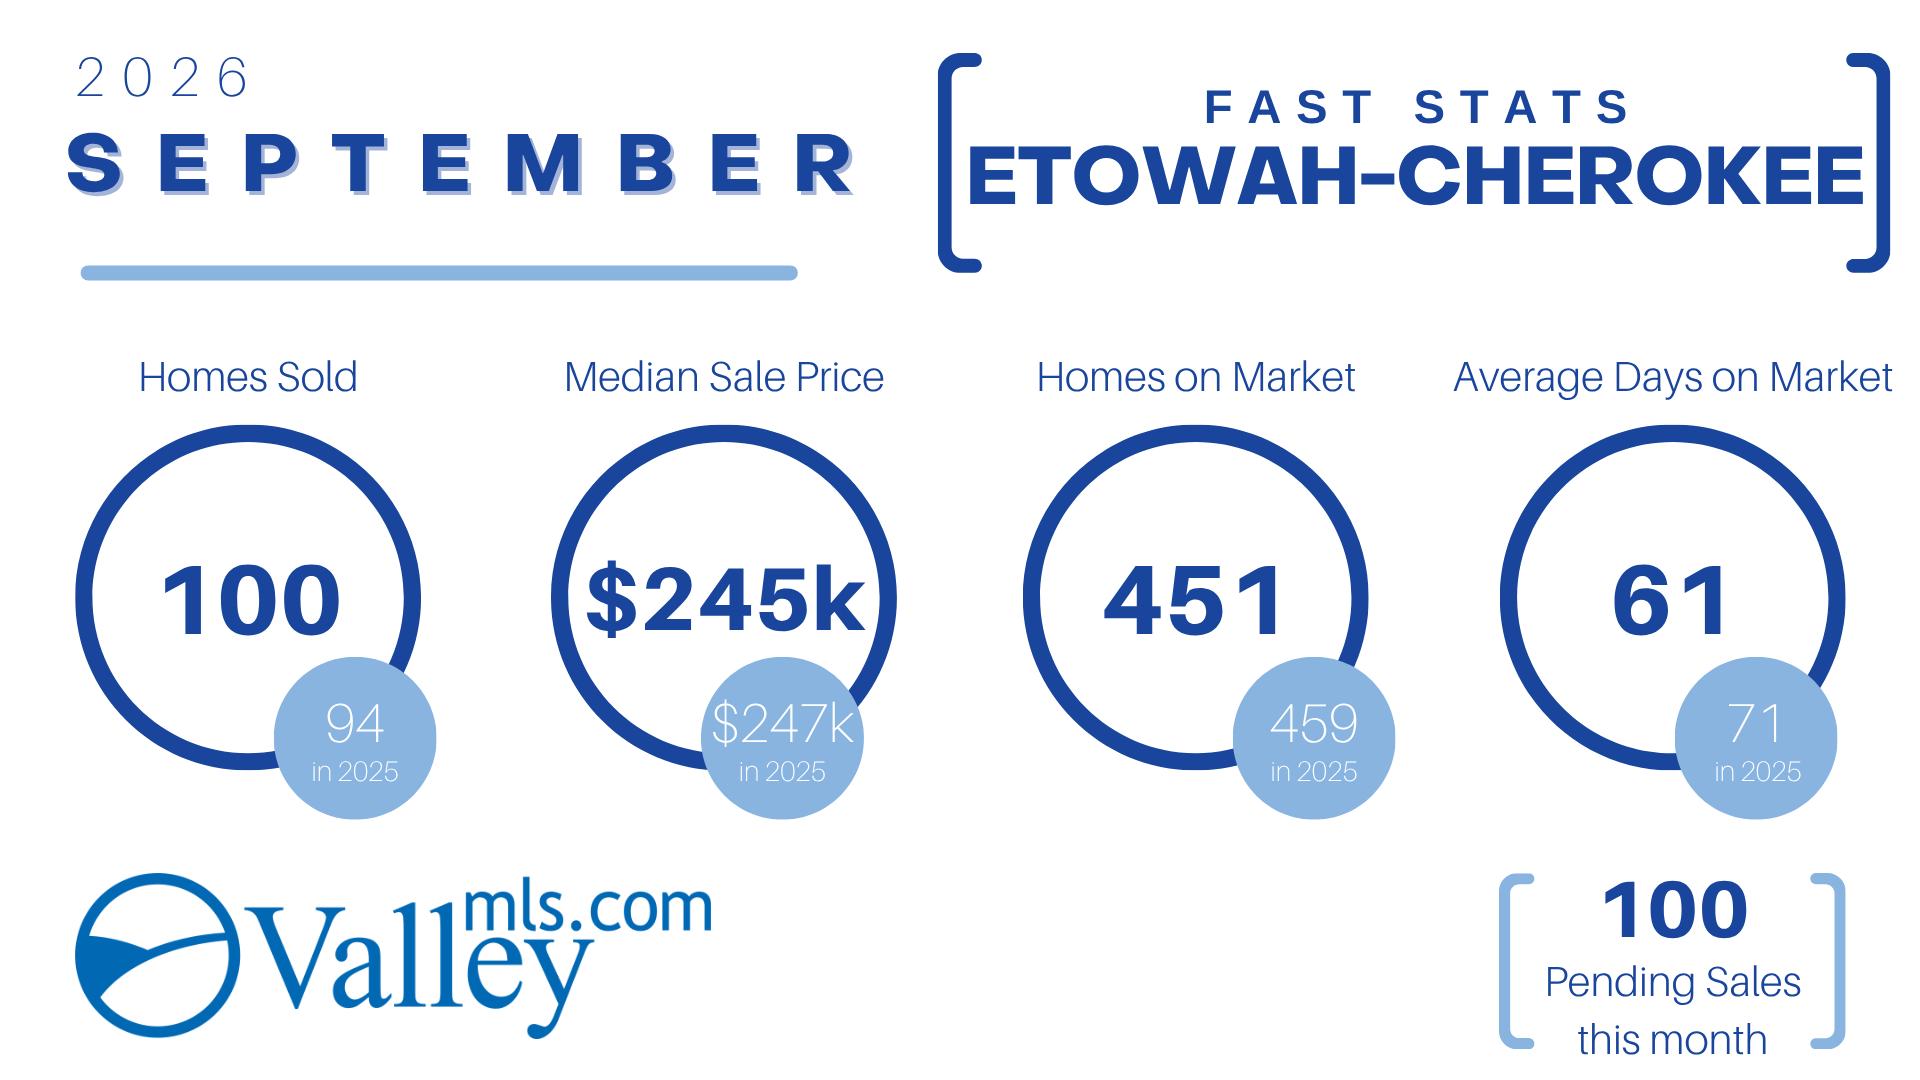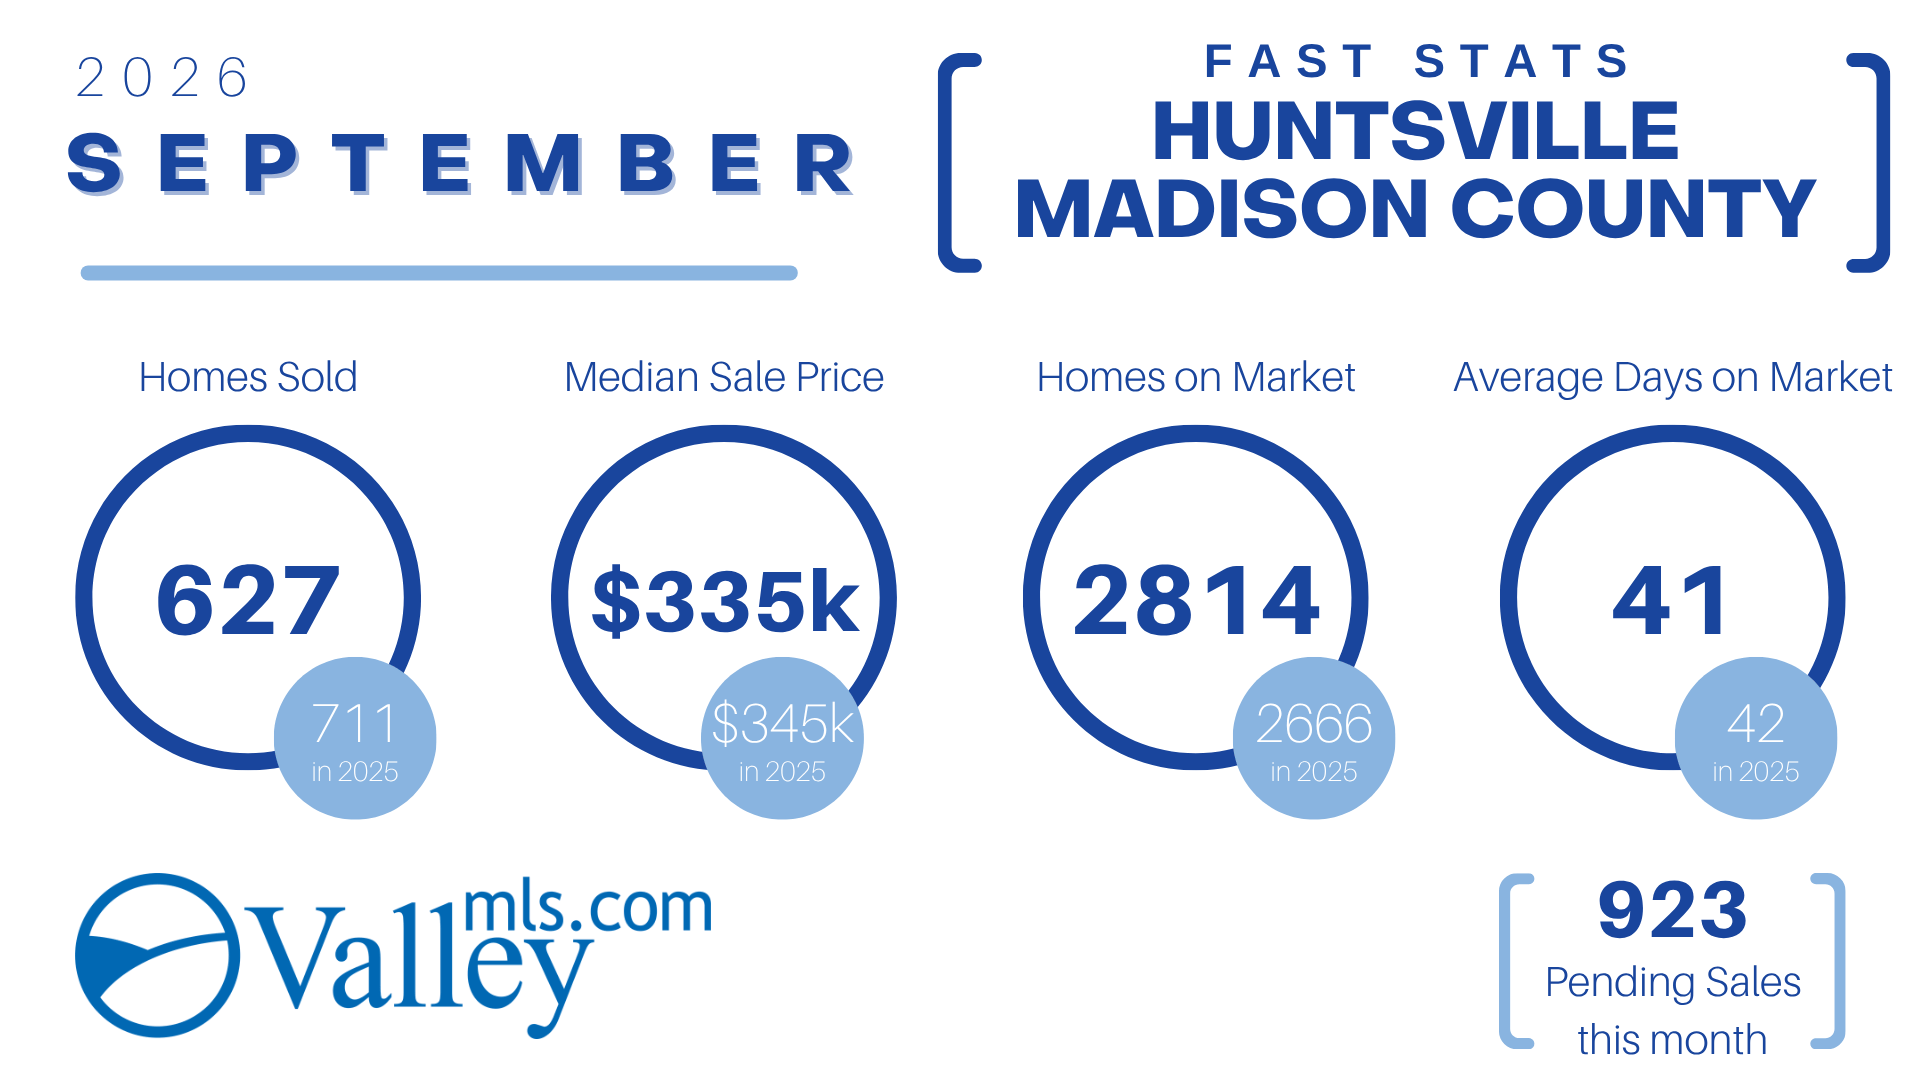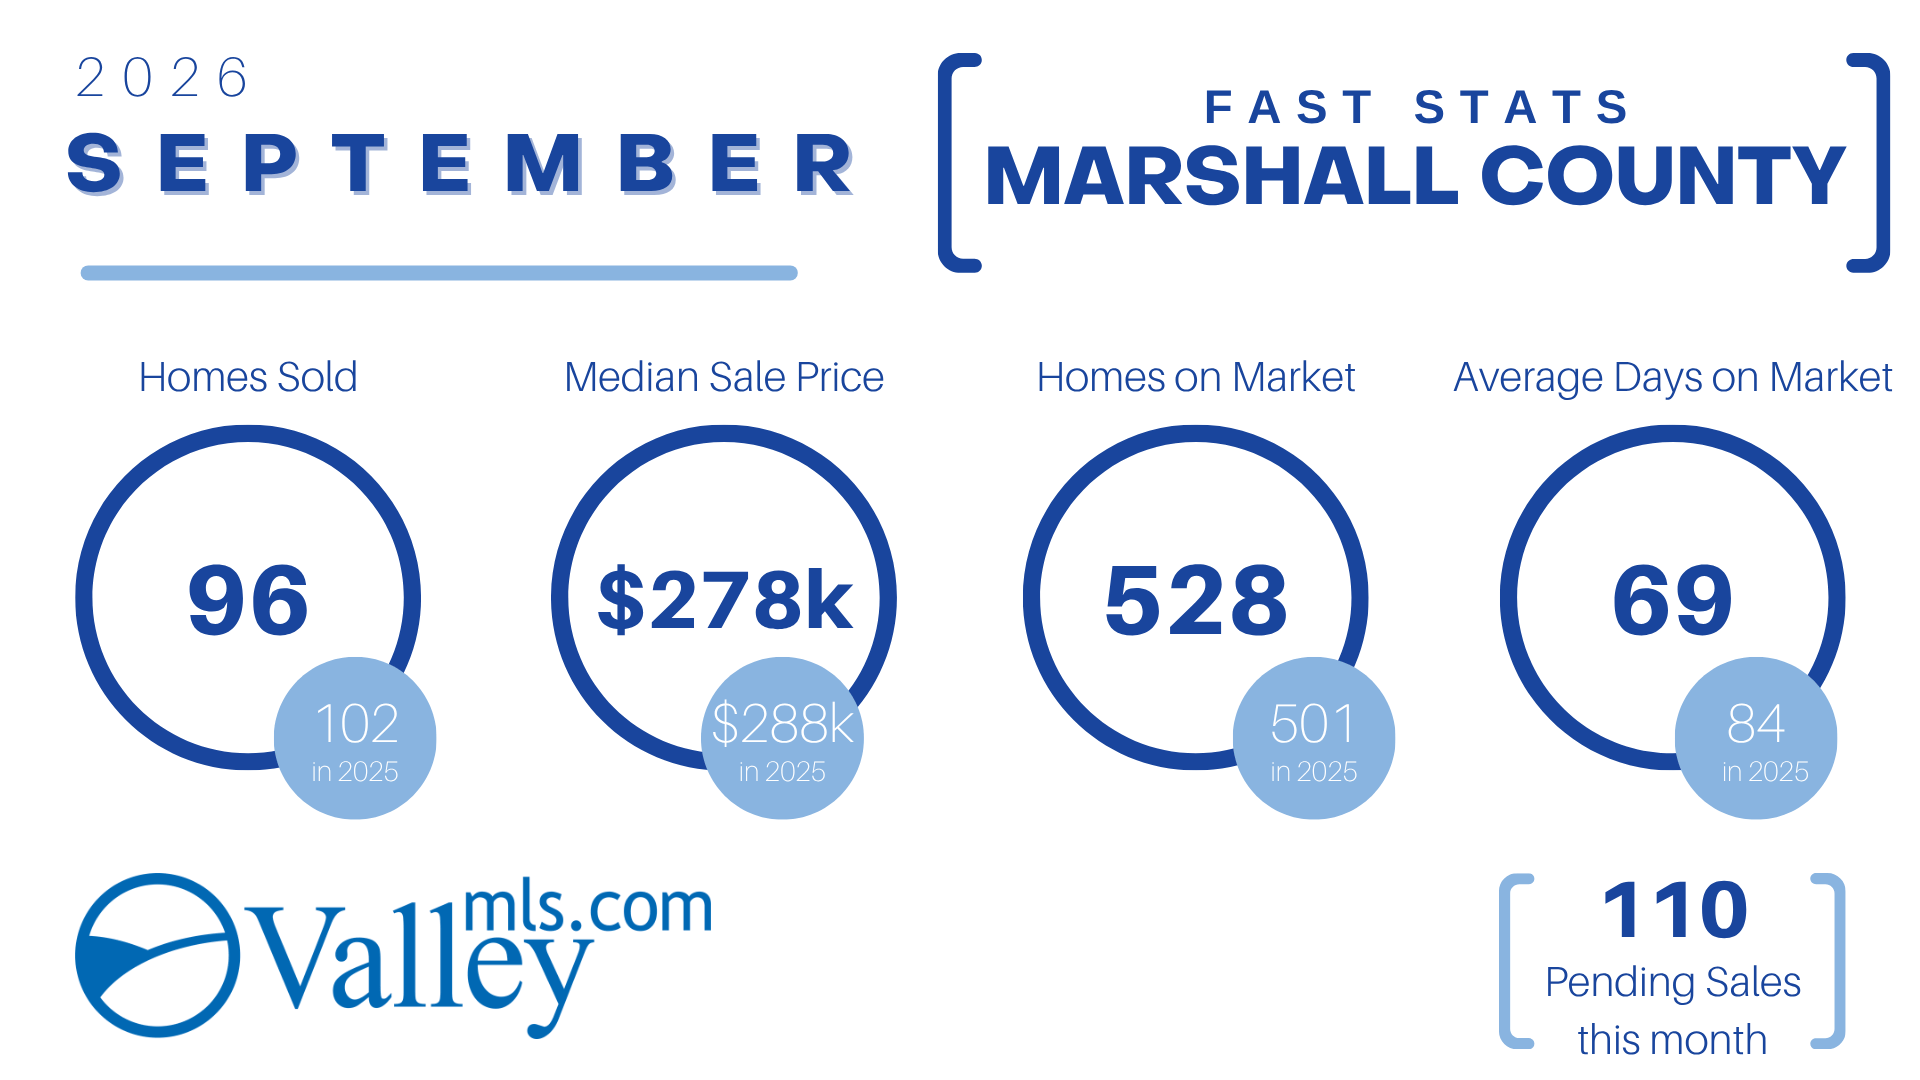Inform | Influence | Empower

Website Search:

News

September 2026 Fast Stats: North Alabama Housing Market Report

10/15/2026

The September 2026 housing data from ValleyMLS.com highlights changing dynamics across the North Alabama real estate landscape. From shifting median prices to inventory fluctuations across individual counties, having a clear understanding of these local statistics equips members of the Huntsville Area Association of REALTORS® (HAAR) to guide clients effectively.
Below is a breakdown of the September 2026 market statistics across all regional areas served by ValleyMLS.

Regional Market Summary (Combined Market)

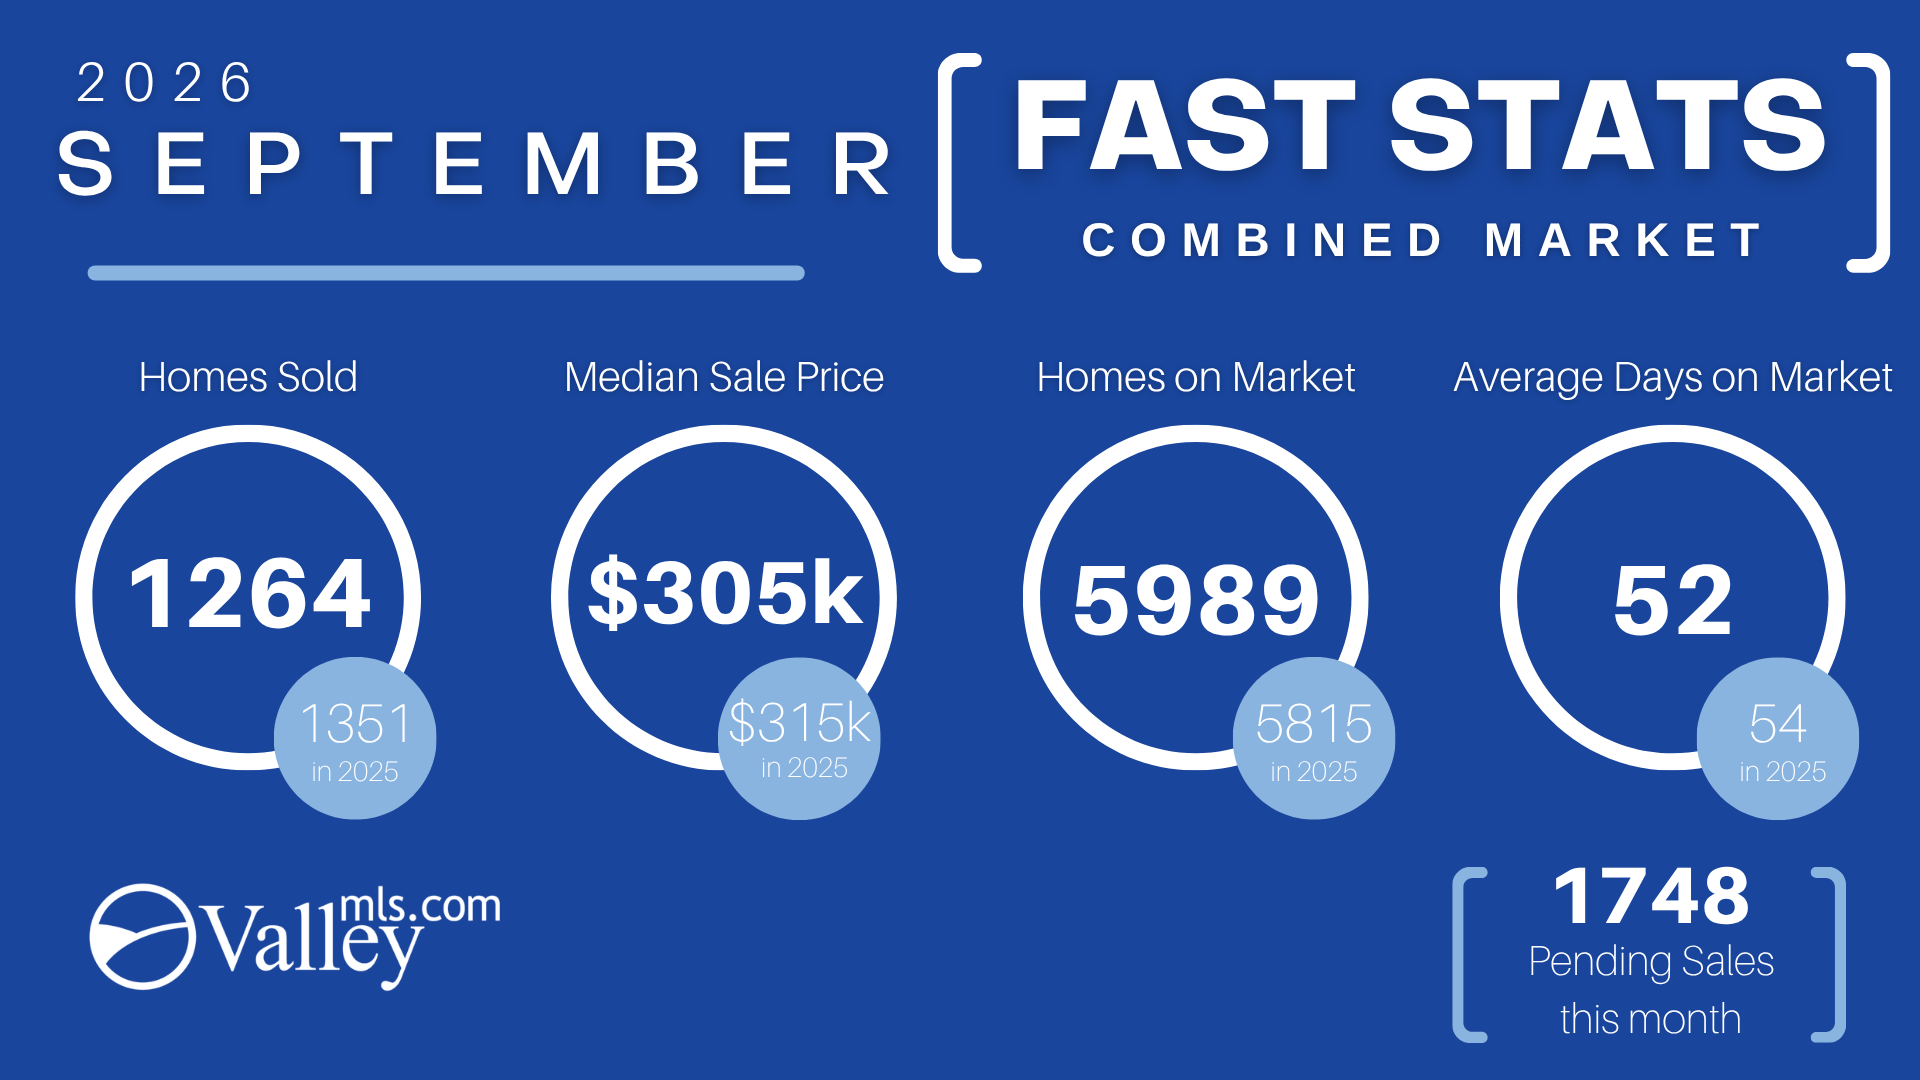
Across the entire combined market area, overall inventory showed steady growth year-over-year while homes sold experienced a moderate adjustment.
  • Homes Sold: 1,264 (vs. 1,351 in 2025)
  • Median Sale Price: $305,000 (vs. $315,000 in 2025)
  • Homes on Market: 5,989 (vs. 5,815 in 2025)
  • Average Days on Market: 52 days (vs. 54 days in 2025)
  • Pending Sales: 1,748

Local Market Breakdown by County & Region

Across the entire combined market area, overall inventory showed steady growth year-over-year while homes sold experienced a moderate adjustment.
  • Homes Sold: 1,264 (vs. 1,351 in 2025)
  • Median Sale Price: $305,000 (vs. $315,000 in 2025)
  • Homes on Market: 5,989 (vs. 5,815 in 2025)
  • Average Days on Market: 52 days (vs. 54 days in 2025)
  • Pending Sales: 1,748

Huntsville & Madison County

Madison County saw a slight cooling in overall sales volume alongside expanded listing options for prospective buyers.
  • Homes Sold: 627 (vs. 711 in 2025)
  • Median Sale Price: $335,000 (vs. $345,000 in 2025)
  • Homes on Market: 2,814 (vs. 2,666 in 2025)
  • Average Days on Market: 41 days (vs. 42 days in 2025)
  • Pending Sales: 923

Athens & Limestone County

Limestone County displayed strong momentum with gains in both completed home sales and overall median sale prices.
  • Homes Sold: 228 (vs. 215 in 2025)
  • Median Sale Price: $336,000 (vs. $326,000 in 2025)
  • Homes on Market: 1,087 (vs. 1,049 in 2025)
  • Average Days on Market: 60 days (vs. 61 days in 2025)
  • Pending Sales: 334

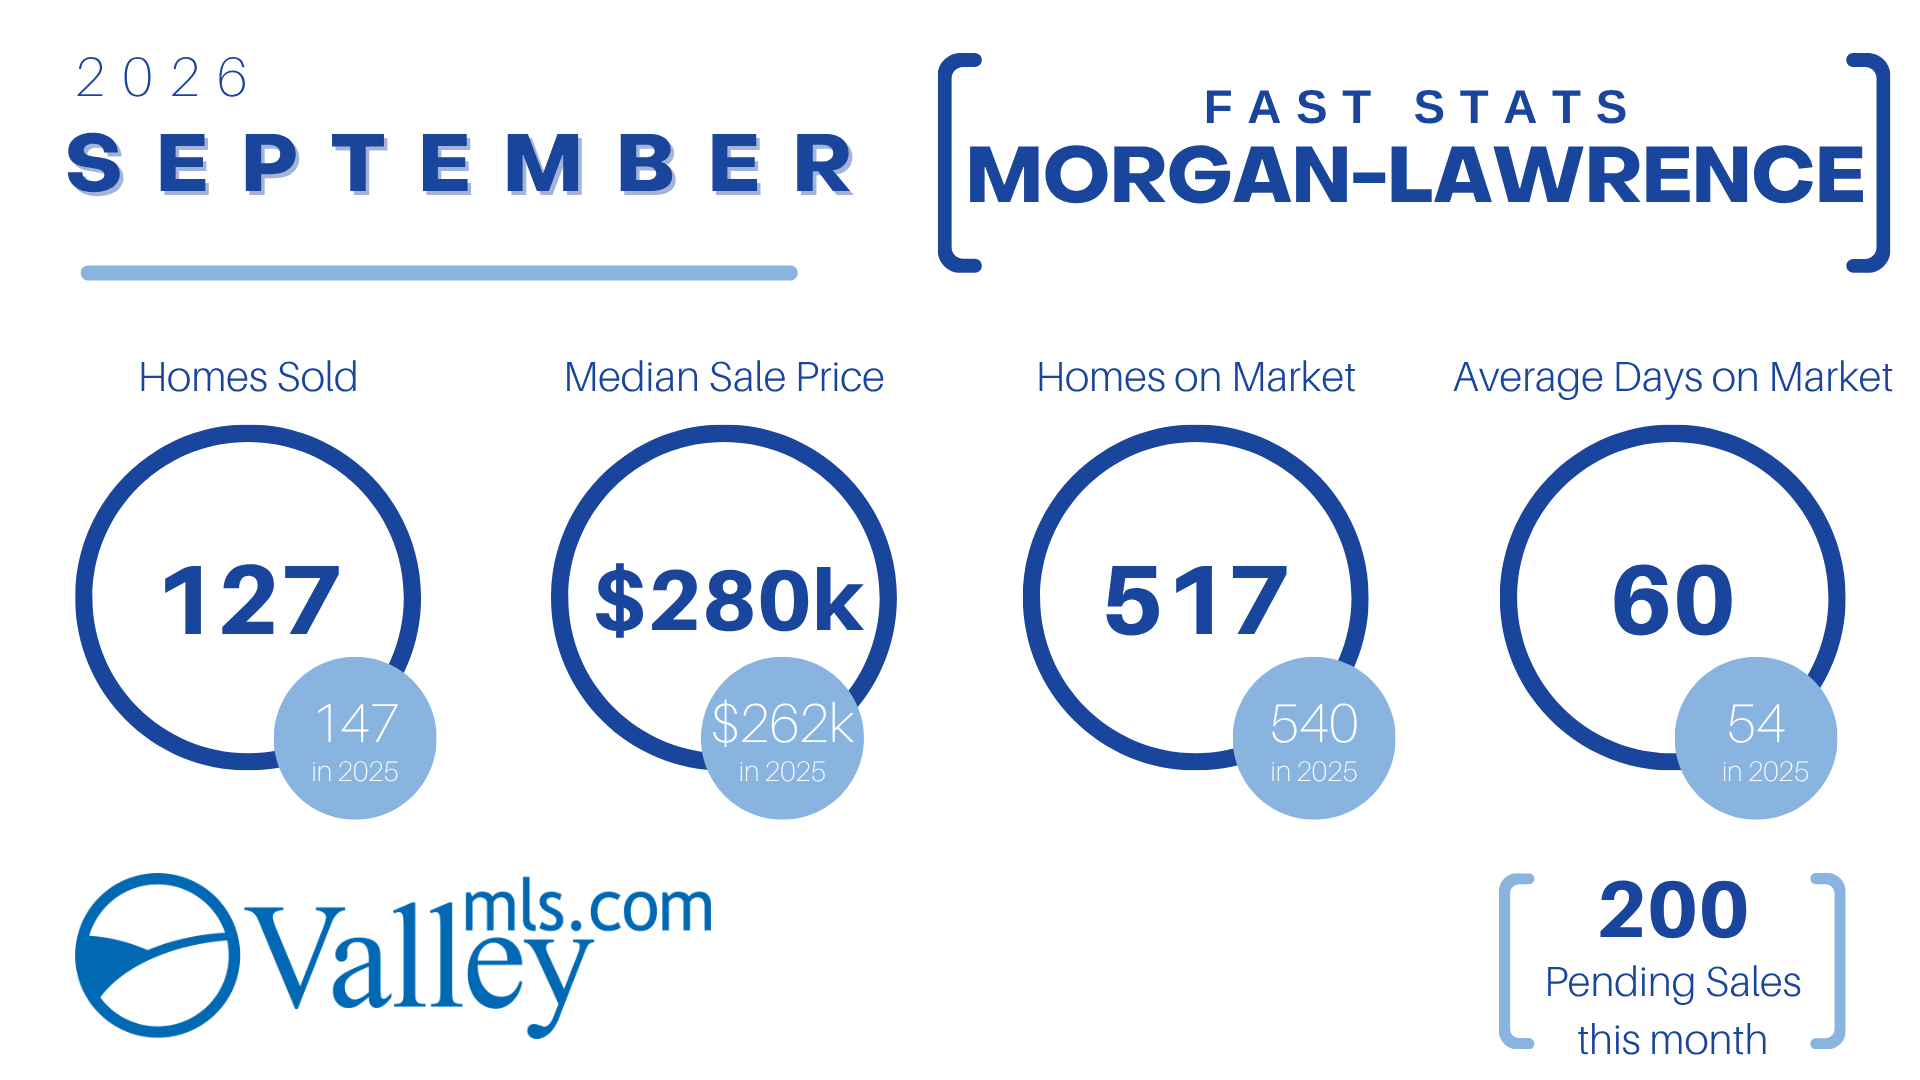
Morgan & Lawrence Counties

Morgan-Lawrence counties posted solid price growth while maintaining active transaction levels.
  • Homes Sold: 127 (vs. 147 in 2025)
  • Median Sale Price: $280,000 (vs. $262,000 in 2025)
  • Homes on Market: 517 (vs. 540 in 2025)
  • Average Days on Market: 60 days (vs. 54 days in 2025)
  • Pending Sales: 200

Marshall County

Marshall County inventory continues to expand steadily, with selling times improving compared to last year.

  • Homes Sold: 96 (vs. 102 in 2025)

  • Median Sale Price: $278,000 (vs. $288,000 in 2025)

  • Homes on Market: 528 (vs. 501 in 2025)

  • Average Days on Market: 69 days (vs. 84 days in 2025)

  • Pending Sales: 110

Etowah & Cherokee Counties

Etowah-Cherokee counties demonstrated gains in sales activity along with faster market velocity.
  • Homes Sold: 100 (vs. 94 in 2025)
  • Median Sale Price: $245,000 (vs. $247,000 in 2025)
  • Homes on Market: 451 (vs. 459 in 2025)
  • Average Days on Market: 61 days (vs. 71 days in 2025)
  • Pending Sales: 100

DeKalb County

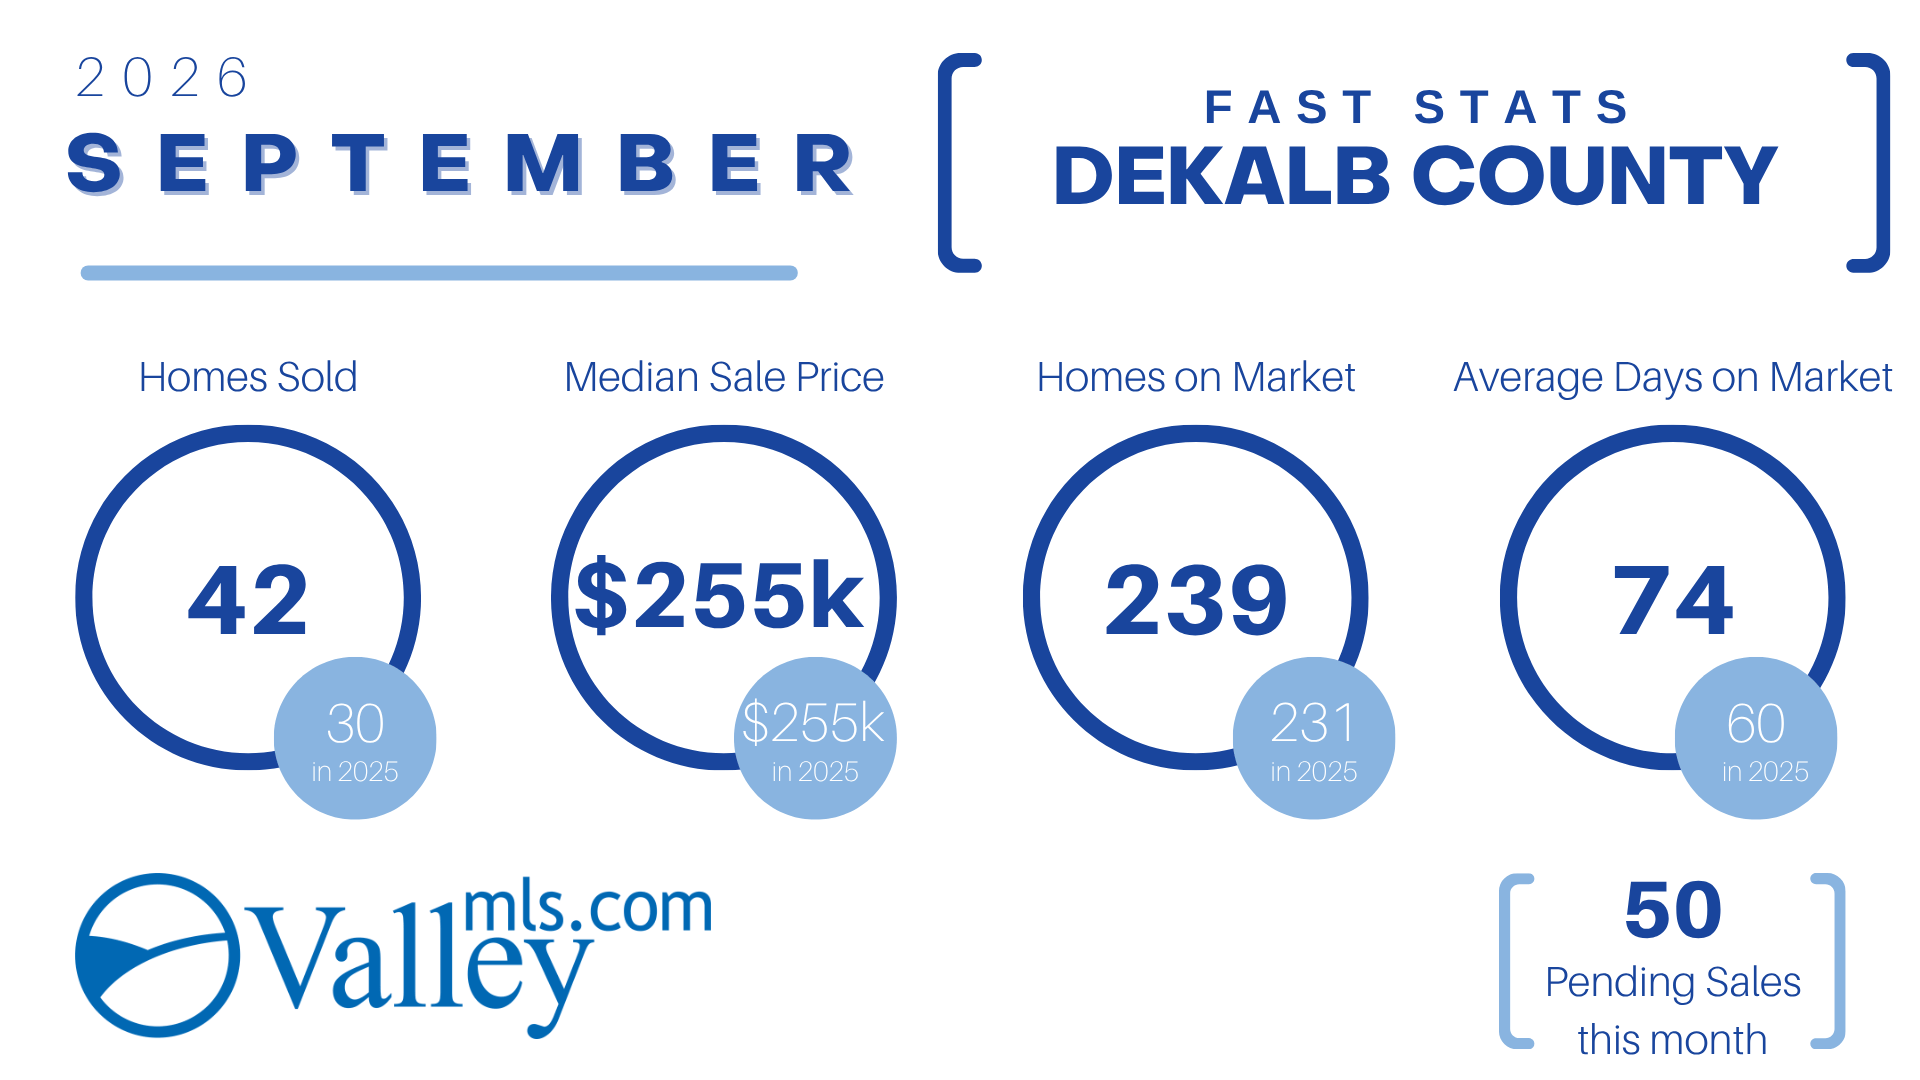
DeKalb County logged a significant rise in home sales compared to September 2025 while price points held firm.

  • Homes Sold: 42 (vs. 30 in 2025)

  • Median Sale Price: $255,000 (vs. $255,000 in 2025)

  • Homes on Market: 239 (vs. 231 in 2025)

  • Average Days on Market: 74 days (vs. 60 days in 2025)

  • Pending Sales: 50

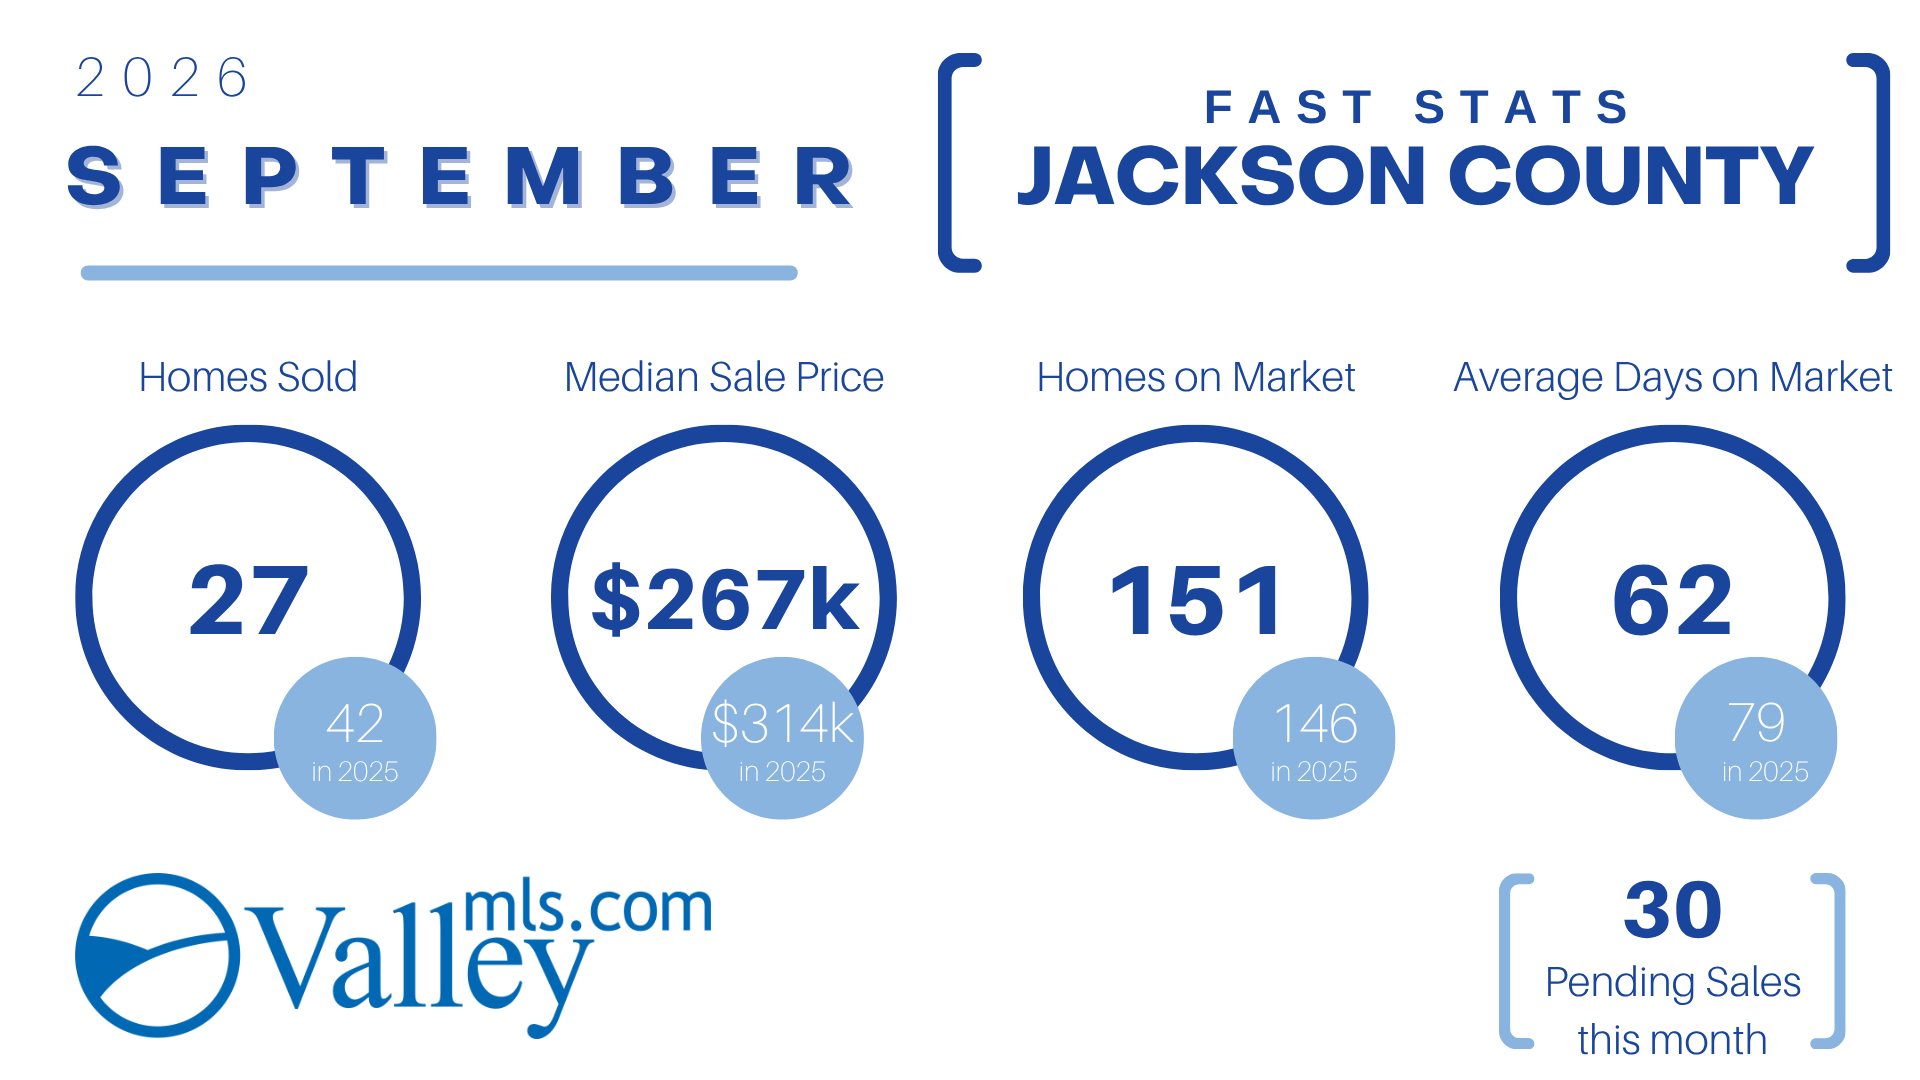
Jackson County

Jackson County saw faster market movement with average days on market decreasing by over two weeks.

  • Homes Sold: 27 (vs. 42 in 2025)

  • Median Sale Price: $267,000 (vs. $314,000 in 2025)

  • Homes on Market: 151 (vs. 146 in 2025)

  • Average Days on Market: 62 days (vs. 79 days in 2025)

  • Pending Sales: 30

Key Takeaways for REALTORS®

  • Rising Inventory Trends: Total active inventory across the combined market grew to nearly 6,000 listings, giving buyers expanded opportunities across North Alabama.

  • Pricing Variations: While regional median prices shifted down slightly from $315,000 to $305,000 year-over-year, submarkets like Limestone County ($336k) and Morgan-Lawrence ($280k) saw notable price growth.

  • Pace of Sales: Homes are staying on the market for an average of 52 days region-wide, holding relatively steady with last year’s performance.

To access more market reports and agent resources, visit the HAAR Member Portal or check market details directly on ValleyMLS.com.

Read More

Weekly Huntsville Real Estate Market Update

08/18/2026

The mid-August market data for Madison County shows divergent trajectories between single-family homes and the townhouse/condo segment. As national trends reflect sluggish sales volumes amid persistent price levels, local activity highlights steady single-family momentum alongside growing inventory in attached housing.

Weekly Snapshot (Week Ending August 8, 2026)

Single-Family Homes: New listings rose 25.7% year-over-year to 191. Pending sales increased by 5.6% to 133, while total available inventory rose 6.6% to 2,247 units.

Monthly Performance Summary (July 2026)

  • Median Sales Price: Single-family median sales prices increased 1.5% year-over-year to $345,000. Conversely, townhouse/condo median prices fell 8.3% to $267,900.
  • Days on Market (DOM): Single-family DOM edged up slightly by 2.4% to 43 days. Townhouses and condos averaged 69 days on market, remaining unchanged from July 2025.
  • List Price Received: Sellers maintained solid pricing leverage, receiving 98.8% of list price for single-family homes (+0.2%) and 98.4% for townhouses/condos (+0.7%).
  • Months Supply of Inventory: Single-family supply contracted slightly by 4.9% to 3.9 months. Townhouse/condo supply expanded significantly by 59.0% to 6.2 months, indicating a shift toward buyer-friendly conditions in that sector.

Key Takeaways for REALTORS®

  • Single-Family Resilience: Demand remains steady for detached single-family properties, with healthy list-to-sale price ratios (98.8%) and sub-4-month inventory levels.
  • Condo/Townhouse Dynamics: Expanding months supply (6.2 months) and longer market times (69 days) point to increased negotiation leverage for buyers looking at attached homes.
  • Macro Environment: The national “lock-in effect” continues to affect inventory broader-scale, but local single-family seller activity showed an encouraging boost in early August.
Read More